To create a budget with gomyfinance.com create budget tools, calculate monthly take-home income, list fixed and variable expenses, assign category limits, include savings and debt repayment, then track spending and adjust the plan each month. Setting up a clear monthly budget helps you control your money, pay off debt, and hit your financial goals without stress.
Many people struggle with budgeting because traditional tools feel too complex. This guide shows you how to use gomyfinance.com create budget features to make a simple plan that fits your daily life.
What Is a Budget and Why You Need One
A budget is a simple plan for your money. It shows how much cash comes in each month and where that money goes. Government resources like Consumer.gov describe a budget as a written plan for monthly spending.
When you do not have a budget, it is easy to overspend. You might run out of money before your next paycheck arrives. A budget helps you make sure you have enough money each month to cover your bills and save for emergencies.
What You Need Before Creating Your Budget
Gather your financial information before you start. Having these items ready makes setting up your budget fast and easy.
Pre-Budget Checklist:
- Pay stubs: Gather recent pay stubs or income records.
- Bank and credit card statements: Collect statements from the past three months.
- Bills and subscriptions: List monthly costs like rent, utilities, streaming apps, and memberships.
- Debt details: Note minimum monthly payments and total balances for credit cards or loans.
- Savings targets: Decide how much you want to save for emergencies or big purchases.
- Irregular costs: Estimate expenses that do not happen every month, such as car repairs or holiday gifts.
How to Create a Budget on GoMyFinance.com
Follow these seven steps to build your budget using GoMyFinance.com.
Step 1: Calculate Your Monthly Take-Home Income
Start with your net income, which is the money left after taxes and payroll deductions. Include regular salaries, freelance earnings, side jobs, and any recurring payments you receive. If your income changes each month, use an average from several recent months to find a reliable baseline.
Step 2: Add Fixed Expenses
Fixed expenses stay roughly the same every month. List these costs first so you know your mandatory financial commitments:
- Rent or mortgage payments
- Utility bills like water, power, and internet
- Insurance premiums
- Childcare costs
- Minimum loan and credit card payments
Step 3: Add Variable Expenses
Variable expenses change from month to month based on your daily choices. Review your recent bank statements to estimate typical amounts for:
- Groceries and household supplies
- Gas and public transportation
- Dining out and takeout meals
- Entertainment, hobbies, and personal care
Step 4: Create Spending Categories and Limits
In GoMyFinance.com, group your expenses into main categories. Start with broad categories like Housing, Transportation, Food, and Personal Spending. Set a maximum dollar limit for each category based on your past spending habits.
Step 5: Set Savings and Debt-Repayment Goals
Treat your savings as a non-negotiable expense rather than leftover money. Set up categories for an emergency fund, retirement contributions, or extra debt payments. Allocating money to savings first protects your financial goals.
Step 6: Track Transactions
Regularly review your spending inside GoMyFinance.com. Check your account weekly to see where your money goes. Move any miscategorized purchases to the correct spending bucket so your totals stay accurate.
Step 7: Review and Adjust Monthly
Your budget needs regular updates to work long term. At the end of each month, compare your actual spending against your planned limits. If you spent extra on groceries, lower your dining budget for the next month to balance the overall numbers.
Choose a Budgeting Method
There are several popular budgeting styles you can apply to your finances. Choose the approach that best matches your personal preferences and spending habits.
| Method | Best For | How It Works |
| 50/30/20 Budget | Beginners wanting simplicity | Put 50% of income toward needs, 30% toward wants, and 20% toward savings and extra debt paydown. |
| Zero-Based Budgeting | People who want full control | Assign every dollar of income to a specific category until your total income minus expenses equals zero. |
| Envelope-Style Budgeting | People struggling with overspending | Set strict cash or category limits for variable expenses. Stop spending when the category hits zero. |
| Spreadsheet Budget | People who dislike app automation | Manually enter every bill and purchase for complete custom control over data tracking. |
Example Monthly Budget
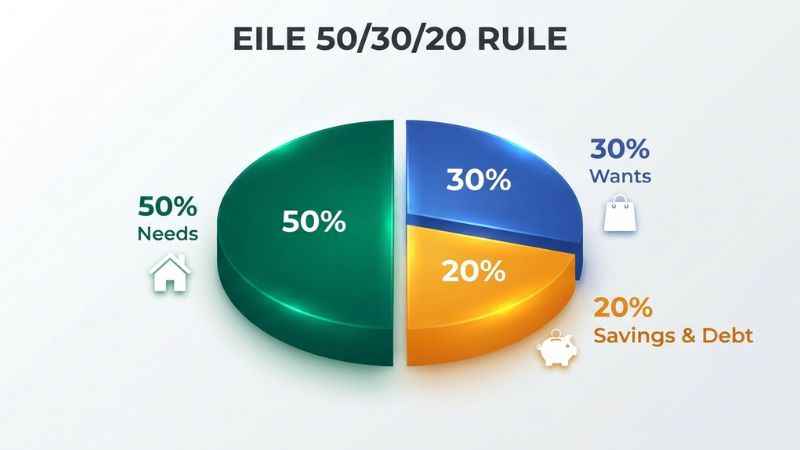
Here is a practical breakdown of a monthly budget using the popular 50/30/20 framework.
| Category | Share | Example Items Included |
| Needs | 50% | Housing, utilities, groceries, transport, insurance, minimum debt payments |
| Wants | 30% | Dining out, entertainment, streaming services, hobbies, shopping |
| Savings & Extra Debt | 20% | Emergency fund contributions, retirement accounts, extra card payments |
Note: These percentages serve as a starting guide. Adjust the numbers to fit your local cost of living and household priorities.
How to Track Spending and Stay on Budget
Creating a budget is only the first step. Staying on track requires regular attention throughout the month.
- Check transactions weekly: Log in every few days to review recent purchases instead of waiting until the end of the month.
- Fix miscategorized spending: Make sure card purchases land in the correct category bucket.
- Set spending alerts: Turn on notifications inside GoMyFinance.com so you know when you approach a category limit.
- Keep a small buffer category: Set aside a small buffer amount you can afford for unexpected small costs that pop up during the week.
- Perform a monthly review: Consumer.gov recommends planning at the start of the month, tracking spending as you go, and using the results to adjust the next month’s plan.
Is It Safe to Link Your Bank Account?
Linking your financial accounts to budgeting apps helps automate transaction tracking, but online security matters. Financial institutions and consumer agencies suggest following these security guidelines when connecting accounts:
[Security Checklist]
[✓] Create a unique, strong password for your budgeting account.
[✓] Enable two-factor authentication (2FA) for logging in.
[✓] Connect only the specific checking or credit accounts you want to track.
[✓] Check whether the app uses read-only access to view your transaction data.
[✓] Check account security settings and review privacy policies regularly.
[✓] Monitor your primary bank accounts for unusual activity.
Common Budgeting Mistakes to Avoid
Avoid these frequent mistakes so your budget stays active and accurate:
- Budgeting with gross pay: Always use your take-home pay after taxes, not your salary before taxes.
- Setting unrealistic spending limits: Do not cut category targets too low right away. Lower your limits gradually.
- Ignoring non-monthly bills: Remember to save monthly for annual costs like car insurance or subscription renewals.
- Forgetting irregular costs: Include occasional expenses like home maintenance, birthday gifts, or holiday travel.
- Quitting after overspending: If you spend too much one month, adjust your categories and try again next month.
What to Do If Your Budget Does Not Balance
If your planned expenses exceed your monthly take-home pay, do not give up. Follow this step-by-step recovery plan to restore balance:
- Verify your income numbers: Make sure you calculated net take-home pay instead of gross salary.
- Separate needs from wants: Check if your mandatory needs exceed your income.
- Trim flexible spending: Cut back on takeout, streaming apps, and non-essential shopping temporarily.
- Pause optional savings: Put non-essential savings goals on hold until your primary monthly bills stay balanced.
- Ask lenders or utility companies if they offer payment help: Reach out to ask if relief options or payment plans are available.
- Update with real data: Rebuild your budget using several months of real bank statements to make future category limits realistic.
Frequently Asked Questions
How do I create a budget for the first time?
Start by writing down your net monthly pay. Next, list all essential bills like rent, utilities, and groceries. Subtract your bills from your income, then assign the remaining money to flexible spending, savings, and debt paydown.
What is the 50/30/20 budget rule?
The 50/30/20 rule divides your take-home pay into three buckets. Allocate 50% of your income to mandatory needs, 30% to wants, and 20% to savings and debt payments. It gives beginners an easy structure to follow.
How much money should I save each month?
The 50/30/20 rule puts 20% toward savings and extra debt payments. If that amount feels too high right now, start with an amount you can afford. Build your savings rate slowly as your income grows or expenses shrink.
Can I budget with an irregular income?
Yes. Calculate your average monthly income using an average from several recent months and use that figure as your baseline. As a practical suggestion, you can base your budget on your lowest estimated month, and put extra money from high-income months into a savings cushion.
How often should I review my budget?
Review your transaction log once a week to catch errors and monitor category limits. Conduct a full budget review at the end of every month so you can adjust spending categories before the next month begins.
Is GoMyFinance.com safe for linking bank accounts?
Linking accounts can be safer when a trusted platform uses encryption and read-only access. Protect your account by using two-factor authentication and a strong, unique password.
What should I do if I overspend in a category?
Do not abandon your budget if you spend too much. Move money from a flexible category, like dining out or hobbies, to cover the gap. Lower your spending limits for the rest of the month to keep total costs balanced.
Do I need to link a bank account to create a budget?
No, linking your bank account is optional. You can enter your income, monthly bills, and transactions manually in GoMyFinance.com.
You May Also Like:
DecoratorAdvice.com: What It Is, What It Covers, and How to Use It to Decorate Your Home
What Is DigitalConnectMag.com? Content, Credibility, and Safety Guide
Joseph Quinn is the founder and editor of Punspa, a technology-focused website covering technology, website reviews, internet terms, and other things worth figuring out online. He writes and edits the site’s technology and web content, with a focus on clear, useful explanations. He also enjoys humor and wordplay, which occasionally leads him to write a pun-related article just for the fun of it.